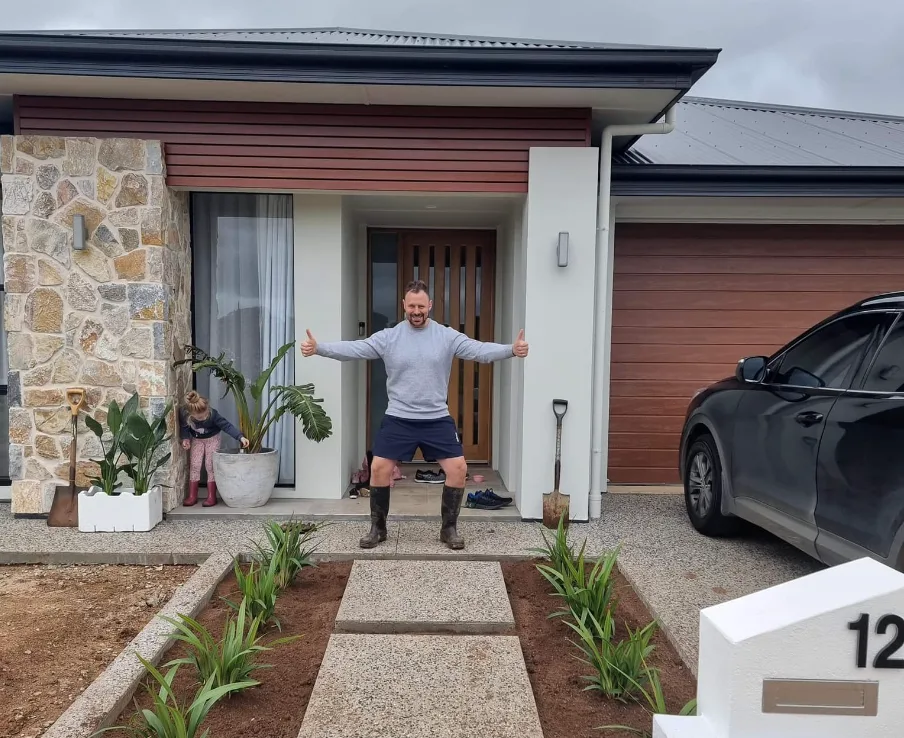
Serving Modbury North
Mortgage Broker Modbury North
Looking for a mortgage broker Modbury North buyers can talk to? Your Mortgage Broker Para Hills arranges home loans across this north eastern suburb, matching your situation to lending policy rather than one bank's shelf.
Looking for a Mortgage Broker in Modbury North?
Nearly all houses here, and approvals keep landing, so construction policy and grants decide more outcomes than price.
Home Loans We Arrange in Modbury North
Each category below follows its own credit rulebook, from refinancing to construction loans:
Refinance Reviews
With forty three point three per cent of dwellings still being paid off, Modbury North runs on refinance activity, so we review structure, offset use and repayment shape against a panel of lenders rather than accepting a maturing fixed rate.
First Home Buyer Loans
A first purchase here starts with grant eligibility on new builds, then established stock, and because a median household earns about $1,596 weekly, lenders generally see workable serviceability once deposit savings have seasoned across at least three months of statements.
Investment Property Loans
Investor lending turns on rental coverage and postcode policy, and a median rent of about $360 weekly supports the yield case, though each lender weighs negative rental gaps differently, so we match the structure to the credit team, not backwards.
Construction Loans
Building activity around Modbury North sits at the seventy seventh percentile statewide, which means staged progress payments, fixed price contracts and lender construction conditions feature in local files more often than in suburbs where every block was built decades ago.
Guarantor Loans
Family guarantee lending lets parents or grandparents support a deposit shortfall using equity in their own home, and it genuinely shortens the savings journey, though guarantors accept real legal and financial exposure, so independent advice comes before any signature, always.
What Makes Financing a Modbury North Property Different
Postcode 5092 is nearly all freestanding housing, yet approvals keep landing, shaping valuations:
Housing Stock
Ninety five point five per cent of dwellings are separate houses and only a sliver are apartments, a profile lenders treat as low density and low friction, which keeps the full lending toolkit open where unit-heavy suburbs lose options quickly.
Valuation Behaviour
Construction approvals continue locally, meaning valuers here see established sales and new build comparables, so a realistic contract price supported by fresh nearby evidence holds up, while optimistic figures on thin evidence invite a valuation shortfall and a smaller loan.
Typical Buyers
Households average two point six people, and a median age of forty points towards established families trading up from a three bedroom home into a four or more bedroom home, alongside downsizers owning outright and first buyers chasing newer stock.
Density Rules
Because apartments barely register here, the dense-stock rules that cap borrowing in higher density postcodes never bite, so the policy questions that matter locally are construction conditions, seasoned deposit funds and how each lender treats a suburb still adding dwellings.
Common Situations We See in Modbury North
Four situations cover most local files, from fixed expiries to the First Home Owner Grant:
Fixed Rate Expiries
Maturing fixed rates look like bad news but are usually genuinely the best moment in years to review the structure, because switching lenders or reshaping the loan during that window often costs far less overall than it ever will again.
Upgrading Locally
Families outgrowing a three bedroom house dominate local upgrade files here, and the usual question is whether to sell first or bridge, which depends on equity in the current home, sale timing confidence and how each lender prices the gap.
New Build Gaps
House and land packages create a two stage deposit problem here: one amount at contract, progress payments as stages complete, plus grant timing, and buyers who model all three together early avoid the cash squeeze that stalls builds mid construction.
Idle Equity
Plenty of long term owners here hold their homes outright and sit on equity quietly earning nothing, and a properly structured release can genuinely fund a renovation, an investment deposit or family support, provided repayments fit comfortably against household income.
How it works
Our Process
Four steps take an enquiry from first call to settlement:
- 1
Speak to a Broker
The first conversation costs nothing and covers your goals, timeline, deposit position and income shape, and if lending is not the right move yet we will say so plainly and explain why rather than parking you in an unsuitable application.
- 2
Capacity and Options Assessed
We verify income, debts, living costs and deposit source, then test your capacity across a panel of lenders, because credit policies differ enough that the same numbers can clear comfortably at one institution and fail outright at the next one.
- 3
Options in Writing
You receive your recommended structure in writing, with the loan features, expected fees, likely timeline and any conditions attached, so nothing important lives only in a phone call and every figure can be independently checked before you commit to anything.
- 4
Application Through to Settlement
Once you approve the structure we lodge, order the valuation, chase conditions and coordinate with your conveyancer through to settlement, then stay in touch afterwards to review the loan whenever rates, lender policy or your own circumstances later shift materially.
Why Choose Your Mortgage Broker Para Hills in Modbury North
A new brokerage earns trust differently, and the page explaining who we are sets out how:
Named Broker
Every client deals with Your Mortgage Broker Para Hills, a credit representative under [LICENSEE NAME], with the representative number 370592 and Australian Credit Licence 389328 published in the footer, so your broker is identifiable and accountable, never an anonymous call centre.
Fees Upfront
Our fee and commission structure is published on this site, so you can see how we are paid before any conversation begins, and any scenario fee is quoted in writing before you decide whether to proceed along that particular path.
Panel Breadth
Since we arrange lending across a panel of lenders rather than one bank shelf, your application goes wherever the credit policy genuinely fits, and where nothing on the panel suits your situation we tell you honestly, without forcing a fit.
Published Process
Process, timelines and document expectations are published before you engage us, which means you can plan around realistic dates, gather every document once, then never wonder what stage your own loan application reached or who is chasing it right now.
Licensing and Compliance
Credit assistance is regulated, and the framework below exists to protect you:
Credit Representative Status
Your Mortgage Broker Para Hills operates as a credit representative of [LICENSEE NAME], which holds Australian Credit Licence 389328, so every recommendation is made under that licence's supervision, and our representative number appears clearly in the footer of every page on this site.
Responsible Lending Obligations
Before recommending anything we are required to make reasonable enquiries about your stated objectives, verify your financial position and assess whether the loan is not unsuitable, obligations that shape every conversation you will have with us, including the awkward ones.
Privacy and Your Data
Personal financial information is collected only to assess and arrange your lending, stored securely, disclosed only to lenders and service providers directly involved in your application, and handled according to the Australian Privacy Principles from first enquiry right through settlement.
How Complaints Work
If something goes wrong, complain to us first and we will acknowledge it promptly and respond within a reasonable timeframe, and if you remain unsatisfied you can escalate to the Australian Financial Complaints Authority at absolutely no cost to you.
Getting a Better Rate on Your Modbury North Loan
The headline number is half the story, and the levers below often matter more to total cost:
Structure Over Headline
Offsets, redraw, repayment frequency and fixed versus variable splits change what a loan actually costs you, and reshaping these first frequently delivers more than chasing a marginal headline figure ever will, so loan structure comes first, before the advertised number.
Timing the Review
Fixed rate expiries, interest only conversions and annual reviews are the natural checkpoints in any loan, and reviewing at those moments rather than whenever marketing prompts you keeps the loan fitted to a life that has probably changed since settlement.
Clean Applications
Lenders price and approve the file in front of them, so trimmed statements, tidied liabilities and documented income shift outcomes, and a fortnight spent organising payslips, statements and card balances regularly changes which credit tier your final application lands in.
Policy Fit Matters
Two lenders can price the same borrower very differently once occupation, property type and postcode policy apply, so we test your situation against panel policy first, then negotiate once we know which credit teams actually want to win the file.
Where we work
Areas We Service
Beyond Modbury North we service Para Hills, Gulfview Heights, Wynn Vale and Modbury Heights:
Questions answered
Frequently Asked Questions
Do you meet clients in Modbury North or work remotely?
Both. We can meet locally or by video call, whichever suits your week, and most Modbury North files run entirely remotely once documents are in.
What is the median price in Modbury North right now?
We do not quote a figure we cannot source, and medians move monthly, so we point you to the latest South Australian sales data instead.
How long does home loan approval take?
A well prepared file commonly reaches formal approval within two to four weeks, though construction and guarantor applications typically take longer because valuations sit inside.
Can you help with a Modbury North investment property?
Yes. We arrange investment lending through the panel, weighing rental coverage against the suburb's roughly $360 median weekly rent, and tax goes to your accountant.
Do you charge a fee for your service?
Our service costs nothing out of pocket, because we are paid commission by the lender after settlement, and any scenario fee is disclosed in writing.
Which lenders do you have access to?
We work with a panel of lenders spanning banks, credit unions and non bank lenders, matching your file to whichever credit policy genuinely fits it.
Mortgage broker for Para Hills and the suburbs around it
Get in Touch
Call (08) 8451 3906 for a free chat, or message Your Mortgage Broker Para Hills for a reply within one business day.